Showing posts with label Buying. Show all posts

Monday, September 22, 2014

Anyone, Anywhere

You know by now that we are your local real estate resource. What you might not know is that we can help just about anyone, anywhere with their real estate needs. Buyers of vacation homes in other states, those relocating into or out of our state, anyone buying or selling real estate across the country even if their move has nothing to do with our local area – we can help them all.

How? In addition to our proven Regional Partnership model which has empowered us to create satisfied clients from Vernon Hills to Manteno, we have also facilitated successful relationships in Indiana, Wisconsin, Arizona, Florida, Wyoming, and more. As a member of the largest real estate company in the country with over 100,000 agents nationwide, we will do the legwork to identify a top-quality agent wherever you or your loved ones need service.


So next time ANYONE you care about has real estate needs, whether near or far, please don’t allow them to fall into the hands of a weak or average professional. Contact us and we’ll make sure they get superior service. Remember our motto: Friends Don’t Let Friends Hire Bad AgentsSM. 

Thursday, November 14, 2013

Getting Your Offer Accepted

As Bob Dylan, said, “The times, they are changin’.” Not too long ago, advice on this topic wouldn’t have been necessary. Since the beginning of this year, however, one of the biggest challenges buyers have faced is wrapping their heads around the fact that they don’t call the shots anymore. Inventory is way down across the board, and for the first time in a long time there are more buyers than sellers. So landing a great deal takes a bit more effort than it has in recent years.

As a buyer, there are certain things you seek in a home. Your needs are unique, but the general characteristics that make a home appealing within a particular area or price range are almost universal amongst buyers. That means you’ve got competition. More and more, well-priced listings are attracting multiple offers within days after hitting the market, and they’re selling for sometimes far in excess of the seller’s asking price. Even without multiple offers on the table, sellers of well-priced listings know if any given offer isn’t all that attractive, they can simply wait for the next one which should be arriving shortly. The seller has their pick of buyers, and it’s up to you to convince them you’re the one!

What sellers are looking for is NOT just the highest possible price, though – they’re looking for the best possible price with the highest likelihood of closing. So what can you do to make your offer more attractive than others?

 Price. Although price isn’t the only concern, it’s still the primary one. Offer high enough, and the other considerations fade out as dollar signs enter the sellers’ eyes.
Financing. Plain and simple, cash is king. Sellers frequently accept lower cash offers because their likelihood of closing is much higher than that of a financed offer. If you don’t have enough cash available, consider such creative methods as 401(k) loans, private mortgages (i.e. to a family member), or for investors, hard money. If you must finance, then use the strongest financing you can qualify for. In order, that would be:
a.       Conventional with 20% or more down
b.      Conventional with less than 20% down
c.       FHA with 10% or more down
d.      FHA with less than 10% down
e.       Rehab loan, such as FHA 203(k)
           Time. Typically, sellers list their homes when they’re ready to sell them. (Duh, right?) So the faster you can close, the faster they can move on with their lives. If you’re buying cash, you can probably close within two weeks. With conventional financing you can shoot for 30 days, and with FHA you’re looking at 30-45. Rehab loans take a minimum of 60 days and can easily drag on for much longer.
      Contingencies. The fewer contingencies, the better. Attorney review and inspection contingencies are built into the contract, but that doesn’t mean they can’t be waived/eliminated. If you must finance the purchase, then you must include a financing contingency – there’s no way around that. A sale of home contingency (you have to sell your house in order to buy the next one) significantly weakens your offer by extending the time frame and introducing a large amount of uncertainty. If you’re competing with other offers and you are contingent-on-sale, you’re very unlikely to win.
       Incentives. Additional personal property, closing cost credits, seller-paid points, home warranties, high tax prorations, pre-closing possession… These are just some of the “perks” buyers can, and frequently have, requested when making offers over the last few years. On top of nickel-and-diming the sellers with these items, they complicate the presentation of the offer. Author Les Brown said, “Shoot for moon. Even if you miss, you’ll land among the stars.” Sorry Les, but in this market if you shoot for the moon as a buyer you’ll likely just end up by yourself in outer space. Keep the perks to a minimum if you want the best price, or to get the house at all.
      Heart strings. Most sellers are human beings, and most human beings have emotions. In some instances, it can work in your favor to submit a “personal letter” to the seller to demonstrate why you love their home and how you’ll take great care of it for many years. When to include a personal letter is a topic for another day!

Here’s the rule of negotiations, of which I’m sure Yogi Berra would approve: Everything other than price costs money. Handing a briefcase full of cash to the seller on the spot is the surest, fastest way to complete the sale, and if you could do that, you would get the house for the absolute lowest price possible (although it’s probably not a great idea for other reasons). Anything beyond that – each extra step, each contingency, each week that must pass before closing, each nugget of uncertainty – must be accompanied by a higher price to compensate the seller for the additional risk. On the opposite end of the spectrum from the briefcase-full-of-cash buyer is the buyer who makes an offer contingent-on-sale, financed with a 203(k) rehab loan, a 90-day closing, and throw in the 1976 Eldorado that’s in the garage. This buyer would have to pay dearly in order for their offer to even be considered.


Keep these considerations in mind when you’re thinking about how to structure an offer. Better yet, hire an agent who can advise you as to how much you can ask for on any given listing while still getting a house you’ll love for the best possible price.

Tuesday, June 4, 2013

Are We in a Seller's Market??

Buyer's market, seller's market... Chances are, you've heard lots of people throwing these terms around without anyone within earshot actually knowing what they mean. Sure, in the general sense, a buyer's market is good for buyers and a seller's market good for seller's. But how, why, and what the hell does it actually mean? Now, I can't define these terms if you're curious about the market for methamphetamines, but if you're talking real estate, I've got you covered.

In the most general sense, for any product or service, one side's market is when there are more people on the other side of the fence than on your side. So a seller's market is when there are more buyers than there are sellers, which means a few things:
- Buyers have fewer choices
- Buyers run into each other more frequently, creating increased competition
- Due to the first two points, buyers find themselves making higher/better offers for any product that substantially meets their requirements, in order to beat out the competition and because there isn't much else to choose from. At the same time, sellers see this happening and price their products higher. These forces result in price increases. Swap the scenarios in this paragraph to envision a  buyer's market.

Ok, now back it up for a second. In order to define buyer's vs. seller's markets in real estate I have to offer a quick lesson in applied math, but I promise I'll keep it short! One of the useful measurements of a market is the absorption rate, which tells us how many homes are selling each month (the number of homes sold over a certain number of months, divided by the number of months). For example, in the past three months in Joliet, 243 homes were sold. So the absorption rate in Joliet over the past three months is 243 / 3 = 81, which means on average 81 homes sell each month. By itself this is not a great indicator of a market, because in Steger there are not even 81 homes available for sale. So to make the absorption rate mean something, we have to factor in the size of the area by dividing the absorption rate into the number of homes that are currently for sale in that area. For example, take Joliet's 577 homes currently for sale and divide it by the absorption rate of 81, and you end up with 7.12. So what is 7.12? We call that the number of months of housing supply. In other words, if no more homes came on the market and homes continued to sell at the current pace, how many months would it take for all of today's inventory to sell? In this case, a little over seven months.

Your next question might be, what does this geeky measurement mean for someone who doesn't care about real estate math? In general, a seller's market is one in which there is less than six months of housing supply, and a buyer's market is one in which there is more than six months of housing supply. (If you're into riding the fence, six months of supply would make it a "balanced market.") Joliet's 7.12 months of supply indicates a market that is mostly balanced but slightly in favor of buyers. And even though in Steger only 28 homes have sold in the past three months, when you divide that into the total active inventory of 65 homes you see there arr 6.96 months of supply in Steger - practically the same as in Joliet.

A few years ago, when the market was in free-fall, in most suburbs there 20+ months of supply. As of the last three months or so, I rarely see them over 10. In one neighborhood in far northwestern Joliet (Greywall Club), where I have a listing that is under contract and ready to close on Friday, the market is like I've never seen it. In the past six months, 12 homes have sold and another 12 are under contract, but only one is available. Take the 12 sold divided by the six-month time period and you get an absorption rate of  2, meaning 2 homes sell each month in this neighborhood. Divide the single active listing by the absorption rate of 2, and you get one-half of one month of housing supply. That's a seller's market to the extreme. And the 12 pending sales show this number won't be going up anytime soon. Case in point: When I listed that home, on my recommendation my client priced her home at the same amount as one down the street which was under contract but was slightly larger and a few years newer. We had a signed contract in less than 30 days for 95% of her asking price. The numbers indicated this neighborhood was in high demand and short supply, and the theory proved true - this sale is rock-solid evidence that prices in that neighborhood are on the rise.

That's not the only place where prices are finally starting to rise, though. Unfortunately, the Chicagoland area is the last major metropolitan area to turn the corner of the housing rebound, but maybe we were just carrying the nation's weight on our broad shoulders. In any event, check out the following data.

MS = Months of supply (remember, <6 = seller's market, >6 = buyer's market)
Median = Median home sale price
'12/'13 = Data covering the three months leading up to 6/3/12 or 6/3/13

                        MS'12   MS'13   % change     Median'12   Median'13    % change
Richton Park    10.44    4.94        -53%             $60,657      $95,000       +57%
Matteson          11.31    5.90        -48%           $124,500    $115,000         -8%
Homewood      10.00    4.98        -50%           $116,800    $130,000       +11%
Orland Park       9.46    7.78        -18%           $258,000    $275,000         +7%
Tinley Park        9.62     6.72        -30%           $210,500    $205,000         -3%
New Lenox       11.17   7.84        -30%           $255,000    $242,200         -5%

The most positive change has been in Richton Park, where since one year ago the months of supply have dropped to half of their year-ago number and the median sale price has increased by a whopping 57%. In all of the areas surveyed, months of supply are significantly less than compared to one year ago. And in three of the areas, median prices have already begun to rise. It's no coincidence that two of the three areas that have experienced the biggest drop in supply have also experience the largest price increases. The others will soon follow.

Back to the question, then, about whether this is a seller's market. Real estate markets are extremely localized, so I never like to paint with broad strokes, but in some areas, yes, this is a seller's market. In other areas where it is still leaning towards buyers, it doesn't appear things will remain that way for long.

Congratulations, we're getting out of this mess.


Friday, April 27, 2012

How to use the MLS mortgage calculator

When considering buying or refinancing a home, affordability is often the most important factor - not the amount financed, but the amount of the payment. The concept of $300,000 isn't something we can easily grasp in everyday terms, but the payment we make every month is immediately applicable to our lives. I often quote estimated payments to home buyers to help them evaluate their decisions, because figuring a mortgage payment isn't exactly simple math. But better than giving you a fish is teaching you to fish, so here's a step-by-step guide on how to calculate estimated mortgage payments using the MLS mortgage calculator.

Depending on whether you're talking about a house or a condo/townhouse, and depending on what type of financing you're using, there are going to be three to five different parts of the payment. The first part is the principal and interest, which is the mortgage itself and is calculated just like a big, long, car note. You'll also be escrowing your property taxes and homeowners insurance, which means you pay your mortgage company 1/12 of the annual cost of each of those expenses every month, they hold it in a separate account (escrow), and when the bills come due the mortgage company pays them. If you're putting less than 20% down, you'll also be paying mortgage insurance. And if the property is part of an association with a monthly fee, such as a condo or townhouse association, you'll also have to figure in the monthly association fee. Although this fee is paid directly to the association, not to your mortgage company, mortgage companies include it as a part of the payment for qualification purposes and you should include it when determining how much you can afford.

Check out the screenshot below; this is the blank slate. We'll start with the simplest calculation and then add the other moving parts.


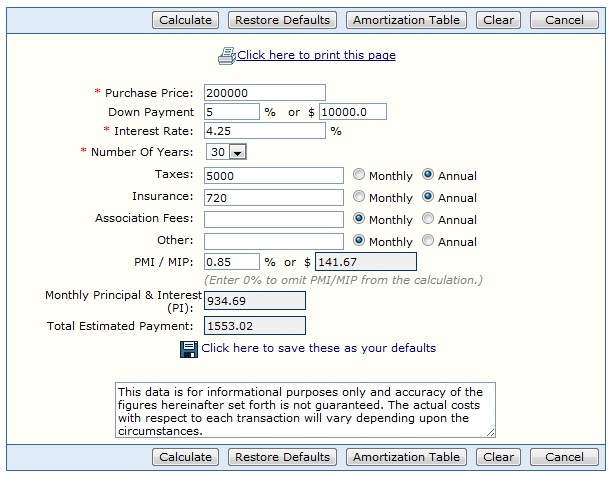
Example #1: $200,000 purchase, 20% down payment. Property taxes of $5,000/yr, and homeowners insurance of $720/yr. Here we will only have principal & interest, property tax escrow, and homeowners insurance escrow. Enter the purchase price, $200,000. Enter the down payment as a percent (20%), and the $ field will auto-populate. Enter the interest rate: As of today I'm entering 4.25%, but the day will come when that will seem utterly outrageous. Leave the Number of Years at 30 unless you're pursuing a 15yr mortgage or other term. Enter the annual property taxes of $5,000. Enter the ANNUAL mortgage insurance of $720 and click the ANNUAL radio button, or if you're premium was quoted as a MONTHLY amount, enter that number and leave the MONTHLY radio button selected. Click Calculate, and voila:


The calculator separates out the principal & interest amount, then provides the total estimated payment including taxes and insurance. Toy around with the interest rate and the price to see how the payment changes - for instance, how much will a .25% increase in the interest rate change the payment? How much will the payment change if you get the house for $195,000 or $190,000 instead of $200,000?

Example #2: Same as Example #1, except now let's say you're getting a 5% down conventional mortgage. So you'll change the down payment to 5%, and you'll have to add mortgage insurance. (For more info on what mortgage insurance is and how it's figured out, read this article.) Today I'm using .85% for mortgage insurance, but this rate will vary depending on the borrower's credit score, amount of down payment, and market conditions. Enter .85% into the PMI / MIP field, which stands for "private mortgage insurance / mortgage insurance premium."


The calculator has also separated out the monthly mortgage insurance amount here. What a nice mortgage calculator.

Example #3: Now imagine the property in Example #2 is a condo with a monthly association fee of $150. Just enter $150 into the Association Fees field, make sure the MONTHLY radio button is selected, and the calculator will include this amount in the total estimated payment. I won't bore you with a screenshot of this one, you get the point.

Example #4: And for the grand finale, we will use an FHA loan. (For more information on what an FHA loan is and why it's different for this purpose, read this article.) Use the same information from Example #2, except change the down payment to 1.75%, and change the PMI rate to 1.25%. The minimum FHA down payment is actually 3.5%, however there is an upfront mortgage insurance premium for FHA loans (separate from what is paid monthly) that can be rolled into the loan as opposed to being paid at the closing. With interest rates so low, it's extremely common in today's market to roll the upfront MIP into the loan. The upfront MIP rate is currently 1.75% of the loan amount, so in order to account for adding that amount to the loan balance, we're taking it off the 3.5% down payment. Here's the result:


So you can see, when comparing Examples #1, #2, and #3, the difference in the affordability of the payment depending on the amount of your down payment and the type of financing you're using.

Hopefully this article allows you to figure out what you can afford when looking at a purchase or refinance. Of course, you'll still need me to set you up with an MLS account and a good loan officer to fill you in on the latest changes in interest rates, mortgage insurance rates, and financing programs available - but this is a start!

Sunday, March 4, 2012

New Down Payment Assistance Program in Park Forest, Chicago Heights

The Illinois Housing Development Authority (IHDA) is piloting a new housing assistance program called Illinois Building Blocks to help stabilize communities hit hard by the foreclosure crisis. The program has three parts:

1. Providing financing to local developers to purchase and rehab 10-15 homes to be resold to to low- and moderate-income families. In Park Forest this will be focused in the "W" and "M" streets. Starting this summer.
2. Providing a $10,000 gift as down-payment and closing cost assistance to home buyers earning less than $84,000/yr (for 1-2 person househould) to $104,000 (for households of 3+). Starting 3/1/12.
3. In conjunction with KeepYourHomeIllinois.org, providing foreclosure counseling, loan modifications, and financial assistance to homeowners unable to pay their mortgages due to unemployment or underemployment.

The communities involved in the pilot program are Park Forest, Chicago Heights, Riverdale, South Holland, Maywood, and Berwyn.

Thursday, February 23, 2012

Your Home Is Not An Investment


I spoke with a new buyer yesterday, and one of the first questions I asked was, "Are you looking to purchase a home or investment property?" The buyer said, "Both." She wasn't talking about buying two houses - she wanted one house to serve both purposes. Anyone else see something wrong with this picture?
I had to get a little more specific by asking the buyer whether she intended to live in the property or not, at which point we determined she was, in fact, looking for a home. The difference is if you live in it, it's your home. If you bought it with the intent to flip it or rent it out - strictly for potential financial reward - it's an investment. But her attitude that her home ought to be equal parts "place to live" and "investment vehicle" has become increasingly common if not prevalent among current and prospective homeowners.
The wild fluctuation in prices and market conditions throughout the recent real estate boom and bust has perverted mainstream America's idea of the purpose a home serves in our lives. Many of us have been fooled into believing our home is an investment account, a commodity to be bought and sold based on market fluctuations. Your home doesn't have a stock ticker symbol, it's not traded on the NYSE, and it is a very illiquid asset. While it's true your home may gain or lose value over time, the primary purpose of owning a home is not - or at least shouldn't be - to make money. 
I've had a number of seller clients close recently for just about the same price they bought the house for, 10+ years ago. After you factor in selling costs, which are substantial, on paper it's a financial loss. But those clients have enjoyed their homes for over a decade, created lasting memories, molded the home to fit their lifestyle, and yes, reaped some financial benefit in the form of tax deductions too. They may not have come out ahead on the resale of the property, but ask them if they gained in other ways from living there and I'll bet their answer is yes.
People have historically bought and sold homes as a lifestyle decision. That means you buy a home when your family's needs change. That includes upsizing and downsizing, marriage and divorce, having children and emptying the nest, bringing in or kicking out extended family, retiring, relocating, or simply looking for a place to settle down. Obviously there ARE financial implications to owning a home, but we would do best to get away from the mindset of putting those implications above our families' needs. Especially now that most experts are predicting a relatively flat market for the foreseeable future, if you're buying or selling a home with dollar signs at top of mind, I'd recommend you reconsider.

Monday, February 20, 2012

So what the heck IS mortgage insurance anyway??


Mortgage insurance, or what you may have heard referred to as "PMI," is not to be confused with homeowners insurance (which is also known as hazard insurance, property insurance, etc.).
Mortgage insurance is an insurance policy that benefits mortgage lenders in the event they have to incur the costs of foreclosing on a property. Lenders require this insurance if the borrower is putting less than 20% down, due to the lender's increased risk in making such a loan. The borrower pays the premium on a monthly basis as a part of their mortgage payment, and the mortgage insurance premium is sent to a mortgage insurance company. If the borrower defaults and the lender has to foreclose, the mortgage insurance company kicks back a portion of the loan amount to the lender.
How much is that premium? It depends on many variables such as property type, credit score, location, current market conditions, etc. But for conventional loans, the range is from about .8% to 1.25%. Example: Take the initial loan amount, let's say $100,000. Multiply it by the rate, for instance .85%, and you get the annual mortgage insurance premium, in this case $850. Divide that by 12 and that's the monthly premium (about $71/mo in this example).
The Federal Housing Administration is essentially a public mortgage insurance company. So when you hear about an "FHA loan," that means the mortgage insurer is FHA. For an FHA loan with a minimum down payment of 3.5%, the annual mortgage insurance rate is 1.15% - higher than MI rates for conventional loans. Additionally, there is an upfront premium due at the closing in the amount of 1% of the loan amount. The upfront MI can either be paid at closing or rolled into the loan. Why pay more for MI by choosing an FHA loan? Because they offer better interest rates and less stringent credit and income requirements than conventional loans, and if you have a non-traditional job/career you're more likely to qualify for FHA.
In some cases, a borrower may qualify to buy out MI (on conventional loans only) by paying a fee at the closing. If the borrower's credit score is high enough (at least 700) and their debt ratio is low enough (45% or lower), they might be able to pay a fee of 1-2% of the loan amount in lieu of paying a monthly MI premium. Using the same numbers in the above example, this would be an upfront fee of $2,000 that would allow the borrower to get out of the $71 monthly premium. In this example, the borrower saves money if they keep the loan for more than 28 months.
Another way to avoid mortgage insurance is to get one mortgage for 80% of the purchase price and a second mortgage for 10% or 15% of the price, which still allows the borrower to put only 5-10% down. This strategy was used, abused, and squeezed to the last drop during the credit bubble, and it is much less common today because of the problems it caused. The problems came about because the second mortgage is always either an adjustable rate mortgage or a variable line of credit with a balloon date - aka "ticking time bomb." [You may have heard of an "80/20" - that's a first mortgage for 80% of the price and a second mortgage for 20%, with no down payment from the borrower. These were all the rage in 2005, then the rates on the second mortgages adjusted 3-5yrs later, payments skyrocketed and homeowners tried to sell. But they owed more than their house was worth because housing prices had already peaked. Enter housing meltdown.]
There is at least one loan program out there that allow borrowers to put down less than 20% but not pay MI. It is called HomePath Mortgage - special financing offered by Fannie Mae only on their foreclosures - and it comes with a minimum 3% down for owner occupants or 10% down for investors, both with no mortgage insurance.
Even if you can't avoid MI, not all is lost. The Homeowners Protection Act of 1998 laid down federal laws that require the cancellation of MI after certain conditions are met. A borrower can request MI cancellation after the loan balance reaches 80% of the initial purchase price, but the lender doesn't have to grant it. However, once the loan balance reaches 78% of the initial purchase price the lender must automatically cancel the MI. Of course there are exceptions - for more detailed info on those, check out this article on the FTC website.
And lastly, the MI premiums you pay may be tax deductible due to the Tax Relief and Health Care Act of 2006. That law created a tax deduction for MI premiums on policies issued on or after 1/1/2007 and was extended for policies issued through the end of 2011. Of course, again, there are exceptions summarized in an article on Bankrate.com, but you should speak with a tax professional to get specifics.
Mortgage insurance isn't looked upon favorably by the public, but it's a necessary evil and I'm glad it's here. Otherwise, every buyer in the nation would need 20% down and the housing market would be infinitely worse off. I'll leave you with a heartwarming, redeeming feature of mortgage insurance companies: MI companies have an interest in preventing foreclosures, because foreclosures mean they have to cough up cash to lenders. So if you ever get behind on your mortgage payment, call the MI company directly and see what they can do.